Residential Property Review – September 2026
| Residential Market Survey – the housing market is stabilising further with buyer demand and agreed sales showing improvement | Mortgage rates – In July, mortgage approvals were 16% below the 2017-19 average and the lowest level since December 2023 | Rental market – In Q1 2026, the average UK landlord portfolio generated £88,454 in gross rental income, a 22.9% annual increase |
RICS Residential Market Survey
The latest Royal Institution of Chartered Surveyors’ (RICS) UK Residential Market Survey indicates that the housing market is stabilising further.
The report shows that buyer demand and agreed sales were still in negative territory in August, but both showed some improvement. The net balance for new buyer enquiries increased for the fifth consecutive month to -19%, marking the least negative reading since January. Sales agreed recorded a similar net balance of -17%, up significantly from -38% in April.
Expectations for sales over the next three months moved closer to neutral territory, rising from -13% in July to -3% in August. The 12-month outlook also improved moderately from +3% to +6%.
In the lettings market, demand continues to outweigh supply; monthly tenant demand recorded a net balance of +18%, while landlord instructions stood at -14%. A net balance of +44% of respondents expects rents to rise over the next three months, up from +33% in July.
Mortgage rates affecting sales
The latest report from Savills shows that higher mortgage rates have impacted sales activity.
In July, mortgage approvals were 16% below the 2017-19 average and the lowest level since December 2023. Sales agreed were also down 6% in August when compared with the pre-pandemic norm.
Completed transactions were 2% higher than the 2017-19 average in July due to a stronger market earlier in the year.
It is expected that transactions will drop in the coming months due to weaker mortgage and sales activity. However, Zoopla reported that buyer searches were up 7% in August. Savills notes that ‘when mortgage rates do fall, there is likely to be a degree of pent-up demand in the market.’
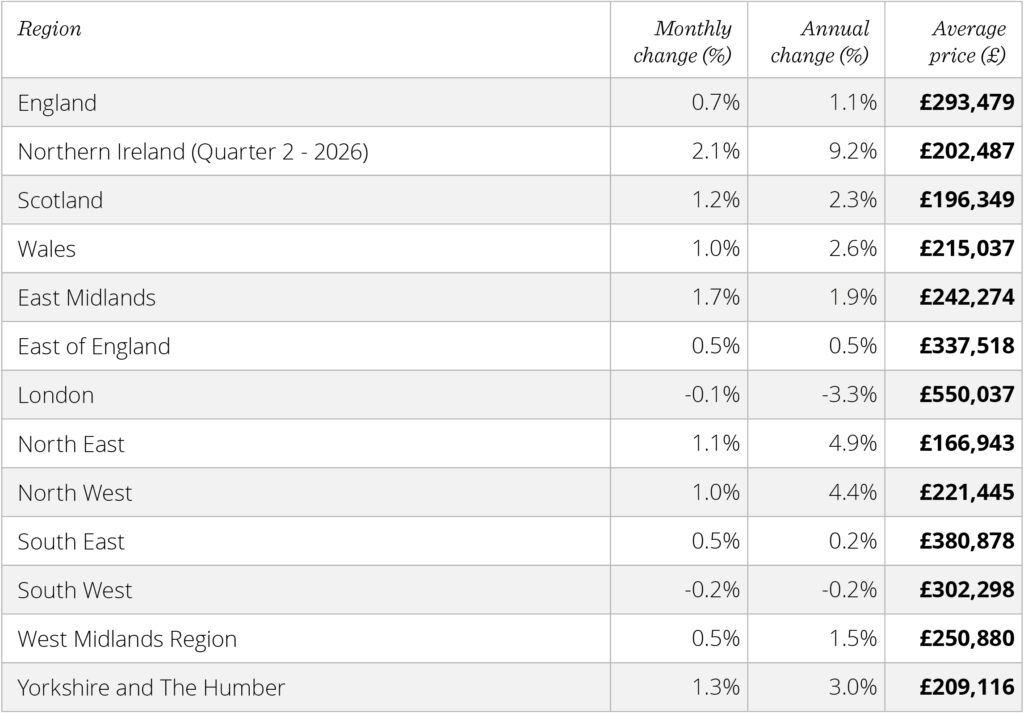
Scotland and the North West continue to lead the way when it comes to house price growth. Localised data indicates East Dunbartonshire (10.9%) recorded the strongest growth in May, while Kensington and Chelsea (-9.1%) saw the slowest growth.
Landlords’ incomes rise
The average landlord’s income has increased over the last year, according to analysis by Rushbrook.
In Q1 2026, the average UK landlord portfolio generated £88,454 in gross rental income, representing a 22.9% increase compared with the previous year. The average landlord owns 7.3 properties, with a combined estimated value of £1.7m.
These figures have remained unchanged over the last year, showing that the increase in rental income has generally not been driven by landlords expanding their portfolios. Instead, the rise is due to higher rents, with estimated rental income increasing from £9,860 to £12,117 per property.
However, estimated buy-to-let mortgage borrowing has also increased by 14.6% over the year and landlords need to account for the ongoing cost of managing properties, which is typically around £139 per month per property.
House prices headline statistics
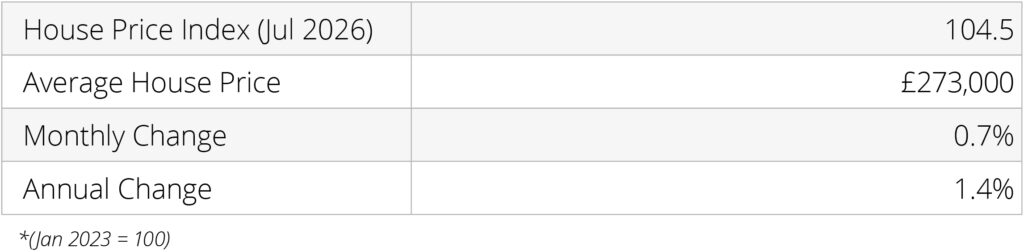
- Average house prices in the UK increased by 1.4% in the year to July 2026
- House prices increased by 0.7% on average between June and July 2026
- The average house price in London was £550,03770.
House prices – Price change by region
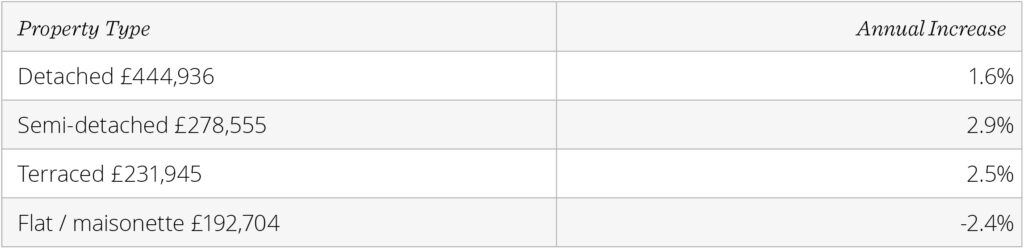
Average monthly price by property type – July 2026
Housing market outlook
“Underlying affordability is improving, as house price growth remains well below earnings growth, although some of these gains have been offset by higher mortgage rates. Nevertheless, this suggests that activity should regain momentum in the quarters ahead providing the energy shock wanes and confidence returns, especially if market interest rates fall back towards pre-conflict levels.”
Robert Gardner, Nationwide’s Chief Economist, September 2026
It is important to take professional advice before making any decision relating to your personal finances. Information within this document is based on our current understanding and can be subject to change without notice and the accuracy and completeness of the information cannot be guaranteed. It does not provide individual tailored investment advice and is for guidance only. Some rules may vary in different parts of the UK.
All details are correct at the time of writing (16 September 2026)
Stay informed with the latest
Receive relevant financial news and updates directly to your inbox.